

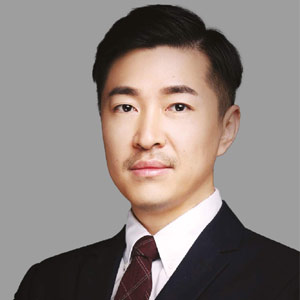
Dan Liu
In an interview with Startupcity, Dan Liu, senior partner, venture and growth capital, CDH Investment, sheds light on the venture capital market in China and the progress Chinese startups are making.
Could you brief us on your roles and responsibilities at your current organization?
I am a senior partner at CDH Investment, one of Asia's leading alternative asset management firms, where I hold the position of managing partner for the venture fund and oversee the growth fund. With a focus on the healthcare sector, I serve as the main project officer and have gained recognition from reputable media and rating agencies in China.
My educational background includes a PhD in cancer biology from Yale University, where I also completed a short-term postdoc at the Department of Clinical Surgery. Prior to joining CDH, I gained valuable experience at Bain and Company in Shanghai, where I used to provide management consulting services to multinational pharmaceutical, diagnostic, and healthcare companies. Currently, I am a board member in many public and private companies.
What according to you are the leading trends and challenges in the industry?
The Chinese capital market differs significantly from many others due to various factors, including cultural, governmental, and economical dynamics, making it more complex. One notable distinction lies in the behavior of entrepreneurs.
In China, many bootstrap their businesses and retain a substantial founder's share even during subsequent fundraising rounds, both before and after the initial public offering (IPO). This helps them maintain control over the company, while investors typically hold a smaller portion and lack control, despite having board seats. This is in contrast with the practices in the US and other regions.
“The Chinese capital market has transitioned to what can be called a 3.0 stage, with a focus on indigenous innovation rather than merely following the footsteps of the US or other developed countries.”
As a result, our investment approach in China requires a long-term commitment of around five to eight years, as the exit channels in the Chinese capital market are not as plentiful or efficient as in other foreign countries. We work closely with founders and entrepreneurs to offer value-added services like strategy consulting, talent acquisition, business collaboration facilitation, and resolving internal team-related issues.
Regarding exit channels and shared liquidity, there are notable differences between China and other foreign countries. In the US and other markets, the IPO pathway is relatively clear, allowing biotech companies to go public even at the preclinical stage or before filing an Investigational New Drug application.
However, in China, although the Star board and Hong Kong stock exchanges have refined their regulations, a company typically needs to reach the clinical stage—which takes about three to four years—before being eligible for public listing. The Chinese market has limited activity in terms of trade sales and mergers and acquisitions (M&A), unlike foreign markets.
This lack of activity in M&A is influenced by various factors, including government regulations, tax considerations, and strategic complexities. Chinese entrepreneurs’ preference to bootstrap their businesses, viewing such deals as limiting their aspirations in combination with other factors has contributed to the relatively inactive M&A landscape in China.
How has the impact of COVID been on the market?
The COVID-19 pandemic has adversely affected the Chinese capital market and the overall economy. Quarantine requirements hindered companies from conducting business and pursuing IPOs, while sectors benefiting from the pandemic represented only a small portion of the healthcare system and economy.
Over the past 12 to 18 months, both the mainland China and Hong Kong stock exchanges experienced significant declines in their indices, with investments in the primary market dropping by approximately one-third compared to the previous year. Although we anticipate a return to normalcy this year, as of today, there has been no substantial bounce back, and the growth observed has not surpassed 25 percent.
How do you create improved investment or funding strategies?
In China's unique healthcare landscape, we capitalize on opportunities by providing affordable, user-friendly, and customized healthcare products. Our focus areas include innovative fields like cell and gene therapy. For instance, I recently invested in a top-ranked macrophage cell therapy platform company specializing in CAR macrophages. This company is set to enter the clinical stage later this year, demonstrating significant progress within a short timeframe.
We also explore sectors like synthetic biology, leveraging China's position as a leading global exporter. By embracing the trend of offering eco-friendly manufacturing, we align with our investment goals and the ESG principles championed by the Chinese government.
What is the future of the market in China?
The Chinese capital market has transitioned to what can be called a 3.0 stage, emphasizing a focus on indigenous innovation rather than merely following the footsteps of the US or other developed countries. Our aim is to become a technology leader in areas where we excel, rather than being a fast follower.
Startups in China are increasingly driven to become market leaders domestically while establishing a strong competitive advantage over foreign investors in pioneering global technology areas. We observe numerous emerging startups exhibiting this potential and actively working towards their goals.
